Blogs · Storm & Insurance
Storm damage and insurance: how we handle a claim in Arizona
The storm is the easy part. The claim is where Arizona homeowners get burned. Here is the order we use after a monsoon, a hail cell in Willcox, or a wind event above the Rim: document first, file second, meet the adjuster on the roof, and never play games with your deductible.
By Evan Baker, owner · August 26, 2026 · 7 minute read
What should I do in the first hour?
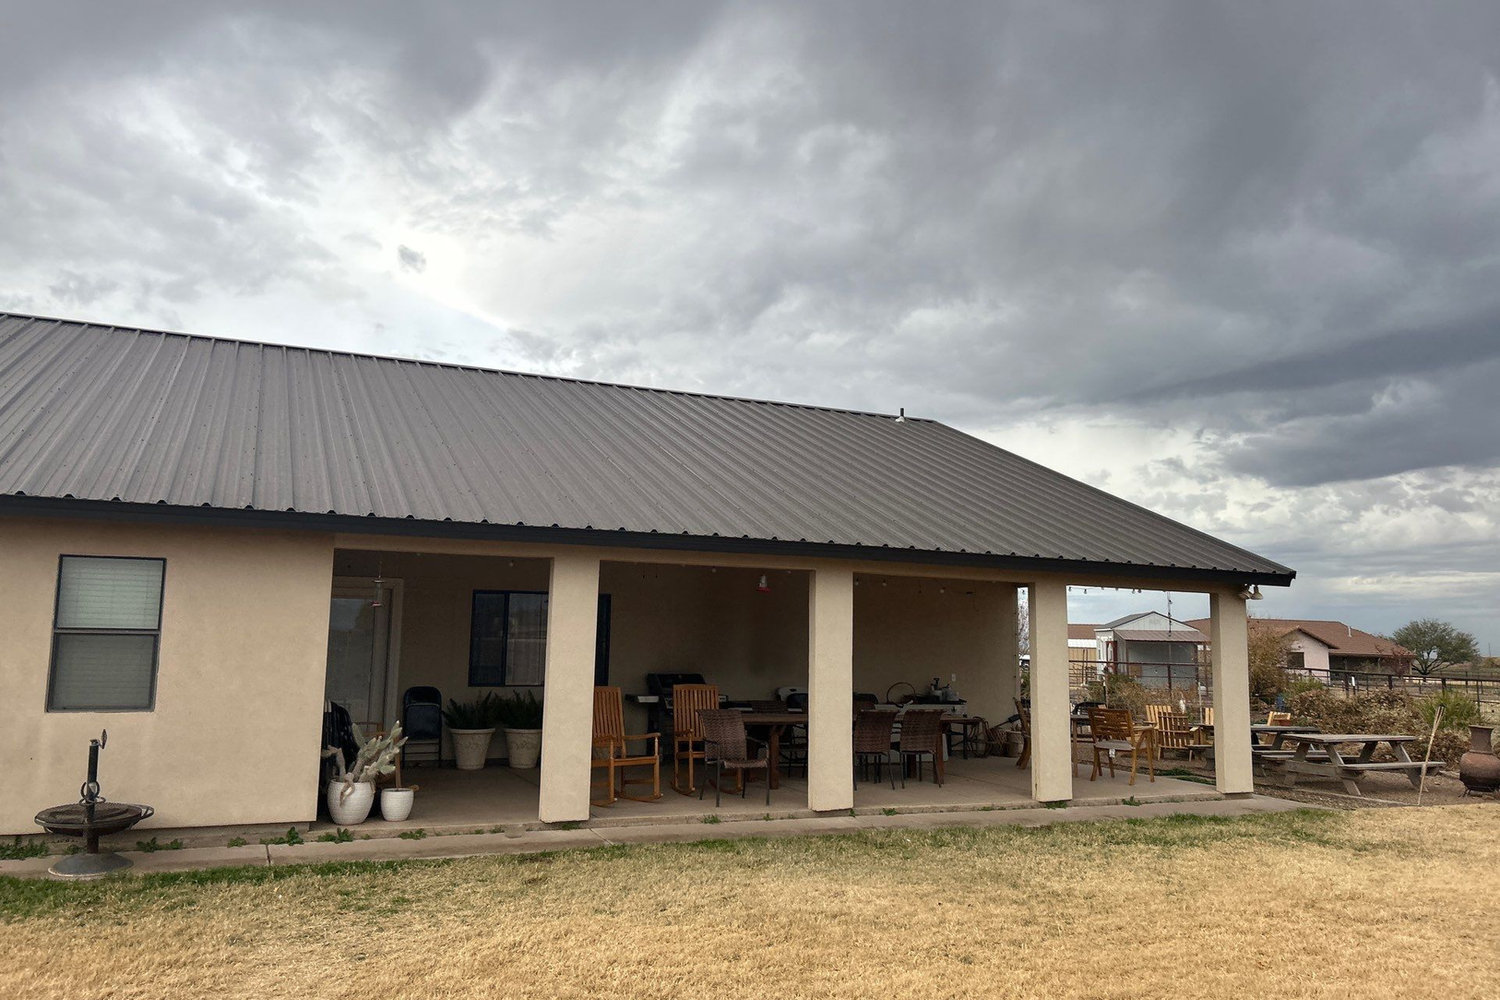
Stay off the roof. Catch water inside. Photograph damage from the ground: each elevation of the house, anything in the yard, every interior stain. Tarp only what you can reach without a ladder. Then call.
A wet slope after a monsoon or a hail cell is how people fall. We get on the roof. You should not. If you have an active leak, call (928) 951-2331 for emergency tarping. A tarp is not a repair. It buys time for the claim to run and for a dry window to do the work.
The full six-step walkthrough after a monsoon cell lives in What to do after a monsoon. This note is the insurance half of that same afternoon.
When do I file the claim?
Report the storm to your insurance company so the claim clock starts. Then call us to document the roof before the adjuster arrives. Do both the same day if you can.
We photograph every slope, every hail bruise, every lifted shingle and bent panel. You keep those photos. They are yours. If the repair is clearly smaller than your deductible, we tell you the repair price first so you can decide whether filing is even worth it. Filing a small claim can raise premiums for nothing.
Why meet the adjuster on the roof?
Adjusters are fair when they can see what we see. Things get missed on a driveway look. We point out damage and code-required upgrades like ice-and-water shield, then leave the negotiating to you and your carrier.
We do not act as a public adjuster and we do not negotiate your policy. That line is on every page of this site for a reason. Repair or replacement is priced the same whether insurance pays or you do: fixed written scope, published ranges on replacements. We do not inflate a scope because a carrier is paying.
Can anyone waive my deductible?
No, and neither can anyone else legally. Your deductible is your deductible. Contractors who offer to absorb it are committing insurance fraud. They are usually the trucks with out-of-state plates that are gone before the first leak returns.
After a storm is when Safford and Show Low hear the knock. We are the other kind of roofer: local address in Thatcher, local crews, and a process that protects the claim instead of gaming it.
How does the weather change by town?
Gila Valley: monsoon microbursts that lift shingles and drive rain under flashing, July through September. Willcox and the Sulphur Springs Valley: hail. Rim Country and White Mountains: wind, snow load, and falling ponderosa limbs.
Impact-rated options matter after a hail claim. Class 4 shingles and metal panels can lower future premiums with many carriers. We show the numbers and let you decide. A tree limb through a Rim Country roof is tarp first, then structural and decking, then roofing, all documented.
Request the inspection or call the office. We call back within 1 business hour.
Claim questions we hear every storm week
Storm & insurance FAQs
What should I do right after a storm damages my roof?
Do you work with my insurance company?
Can you waive my deductible?
Is my price different if insurance is paying?
Should I file a claim for minor damage?
Document the roof before the next cell.
Free inspection and photo set. Emergency tarping quoted by phone at (928) 951-2331.